

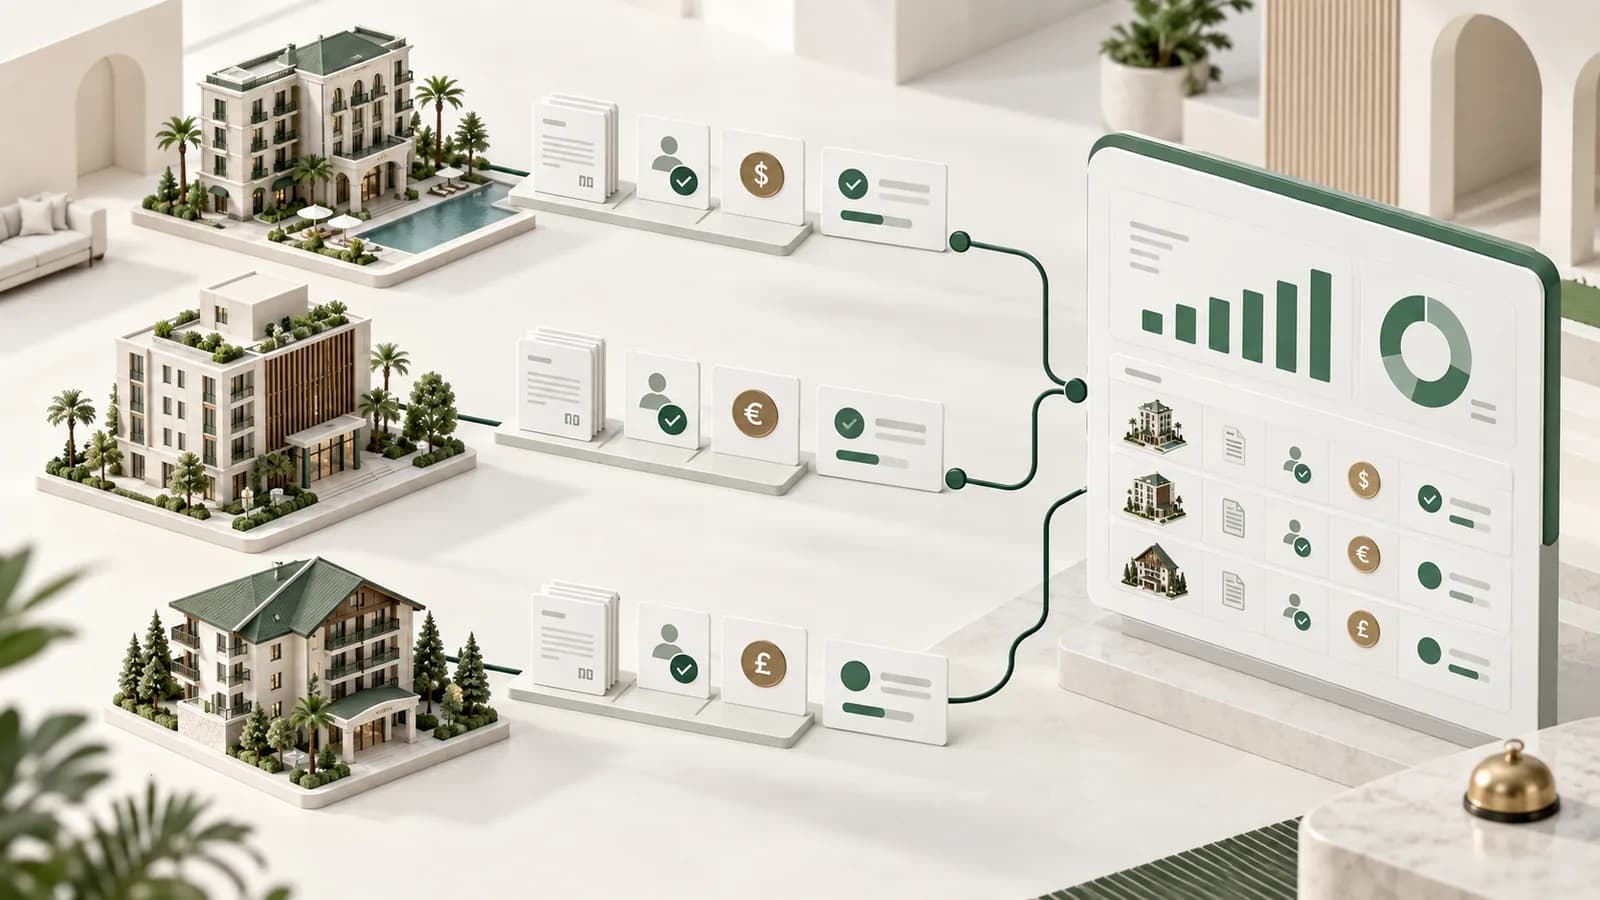
A hotel group does not have one billing flow multiplied by the number of properties. A room account, banquet event, corporate account, management fee, long-stay arrangement, travel-agent commission, vendor recovery and intercompany charge can each begin in a different system and require different evidence.
Centralizing everything without retaining property context weakens control. Leaving every property completely independent makes group oversight, consistent policy and cash visibility difficult. The practical model is federated: common standards and consolidated reporting, with local identity, authority and exception ownership preserved.
The objective is not to force every charge through one identical route. It is to make each route explicit enough that finance can explain who was billed, by which entity, for what source activity, under whose approval and with what collection state.
Define the billing map before selecting automation
List every charge type by source, customer, issuing entity, currency, tax profile, frequency, evidence, approver and delivery channel. Include direct guests, corporate customers, groups and events, long-stay occupants, owners, partners and internal group companies where relevant.
Separate guest folio settlement from accounts-receivable invoicing. A charge paid at checkout follows a different control path from a corporate invoice issued after an approved stay, centrally billed event or contracted period. The systems may share data, but their states should not be treated as interchangeable.
Name the system of record for reservations, point-of-sale activity, events, contracts, customer master data, invoices, payments and the general ledger. The map will expose duplicate ownership before an integration makes it faster.
Preserve property and legal-entity identity
Every invoice should carry the correct issuing entity, property, document sequence, currency, bank instruction, tax configuration and contact details. These values must follow controlled master data rather than whichever template an operator used last.
Property identity also belongs in group reporting. A central team should be able to filter open receivables, disputes and collection promises by property and entity without combining legally separate balances. Shared customers need a consistent identifier while their contracts and invoice destinations remain specific.
Use effective dates for entity details, rates and billing contacts. A current address or bank account should not rewrite an already issued document or its delivery evidence.
Control source-to-invoice hand-offs
A property management system can show a completed stay, but that alone may not authorize a corporate invoice. The billing record may also require a company agreement, purchase order, guest or event reference, approved incidentals, tax details and evidence that exceptions were accepted.
Retain source identifiers on the invoice or connected billing case so a reviewer can move from the charge back to the stay, booking, event or contract. Totals should reconcile by source population, not only by comparing one exported grand total with another.
Late adjustments need an explicit route. Decide whether they reopen a folio, create a new invoice, require a credit and replacement, or move to a later period under policy. Never edit an issued invoice merely to make systems agree.
Standardize approvals without blocking every property
Set risk-based approval rules. Standard contracted room charges may pass after automated validation, while manual rates, waived fees, unusual taxes, event changes, high values, credits and entity overrides require named review.
Give property teams authority within documented limits and route exceptions to the appropriate central or regional owner. Approval should add a decision, timestamp and reason to the record. It should not become a generic inbox in which invoices wait without an accountable next step.
Monitor repeated overrides by cause and property. A pattern of missing purchase orders or late event changes may signal an upstream commercial problem rather than a need for more finance reminders.
Build consolidated visibility from controlled local states
The group view should distinguish draft, awaiting evidence, awaiting approval, issued, delivered, disputed, promised, partly paid, paid and written-off states. Use definitions that every property applies consistently.
Age alone does not explain risk. Add customer, property, reason, owner, next action and promised date to receivables reporting. A central team can then support material or stalled cases without taking routine ownership away from the property.
Reconcile invoices and receipts at both property and group levels. Central cash collection may require allocation back to several properties or invoices; preserve the original receipt, remittance evidence and unapplied amount until every portion has an approved treatment.
Protect guest and company data through role design
Multi-property access should follow responsibility. Front-office staff, event teams, property finance, regional controllers and group finance do not need the same ability to view customers, alter master data, approve credits or change bank instructions.
Separate the right to prepare from the right to approve high-risk changes. Review access when staff move properties or roles. Keep an audit trail for customer, entity, payment instruction, tax and invoice changes.
Treat data retention, payment information and jurisdiction-specific invoice requirements as governed matters. Software configuration supports the policy but does not decide the legal treatment.
Run month-end as a controlled group cycle
Publish property cut-offs for stay completion, event sign-off, contract changes, credit requests and intercompany inputs. Compare the expected billing population with prepared invoices so missing records are visible even when no draft exists.
At release, separate invoices that were issued, returned, held or cancelled and retain the reason for each. A central completion percentage is useful only when it does not conceal material exceptions at one property.
After release, reconcile source totals, invoice totals, delivery outcomes and accounting hand-off by property. Review repeat causes across the group and repair upstream processes while leaving local teams accountable for current cases.
A representative operating scenario
Consider a group with a city business hotel, a resort and an extended-stay property. One corporate customer uses all three during the same month, but each property belongs to a different issuing entity. The city hotel bills room nights, the resort bills a contracted event, and the extended-stay property receives one central payment that references several invoices.
The central dashboard may show the customer's total exposure, but the documents cannot be collapsed into an unexplained group balance. Each invoice retains its property, entity, contract reference and owner. The payment is recorded once, allocated from remittance evidence and leaves any unsupported remainder visible as unapplied cash.
Five-point case review
Does every charge map to a source, customer, property, issuing entity and evidence requirement?
Are master-data changes controlled with owners and effective dates?
Can local teams resolve routine work within defined approval limits?
Does the group view preserve property, reason, owner and next action?
Can finance reconcile invoices and payments at both property and consolidated levels?
Put the decision into practice
Pilot the control model with two properties that have meaningfully different billing profiles. Trace a direct stay, corporate stay, event, credit, central payment and dispute from source to accounting. The group view should consolidate status while every record retains its property, entity, evidence and owner.
Use the exceptions found in the pilot to finalize master-data ownership, approval thresholds, integration retries, close cut-offs and escalation rules before rolling the model across the group.
Document the result as a property onboarding pack: required master data, source mappings, role assignments, approval limits, billing calendar, exception reasons and reconciliation checks. Require every new property to pass the same sample transactions before joining group reporting. This keeps expansion from turning local variation into unexplained consolidated numbers.
Evidence
Sources and scope
- Invoicera multi-entity billing
Provides product context for multi-entity billing. The hotel scenario is illustrative and does not imply a hotel-management integration. The operating framework in this article should be adapted to the group's systems, jurisdictions and accounting policies.
Continue in context